FED RATES ARE UP – What does that mean for your business?
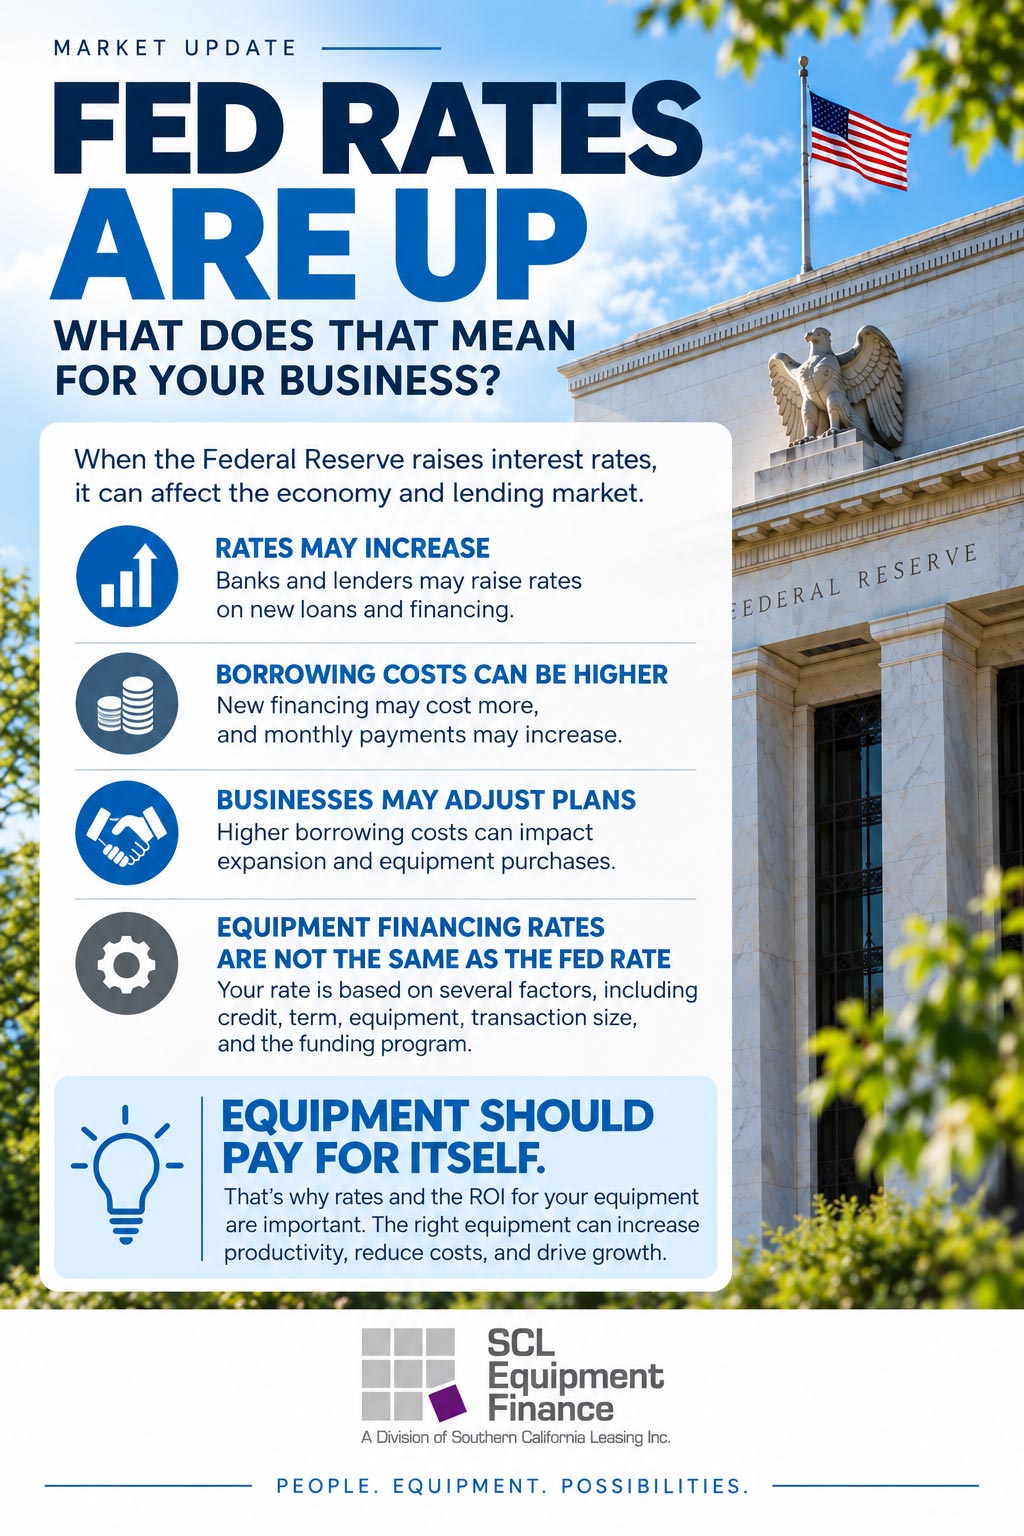
Fed Rates are up

When the Federal Reserve raises interest rates, it can affect the economy and lending market.

RATES MAY INCREASE
Banks and lenders may raise rates on new loans and financing.

BORROWING COSTS CAN BE HIGHER
New financing may cost more, and monthly payments may increase.

BUSINESSES MAY ADJUST PLANS
Higher borrowing costs can impact expansion and equipment purchases.

EQUIPMENT FINANCING RATES ARE NOT THE SAME AS THE FED RATE
Your rate is based on several factors, including credit, term, equipment, transaction size, and the funding program.

EQUIPMENT SHOULD PAY FOR ITSELF
That’s why rates and the ROI for equipment are important. The right equipment can increase productivity, reduce costs, and drive growth.

Bank Loans vs Equipment Financing | What is the Difference?

Understanding the Difference

Banks play an important role in business financing, especially for established companies with strong financials. However, when flexibility, speed, creative structuring, or preserving bank credit lines is important, equipment financing can often provide a more effective solution

Traditional Bank

  • Balance sheet lending with one credit policy
  • Best suited for established businesses with strong financials
  • Limited flexibility outside credit parameters
  • Less adaptable to startups or unique credit situations
  • Efficient when the deal fits the box
  • Can tie up bank lines of credit
  • May require blanket liens on business assets
  • Annual financial reporting requirements

SCL Finance Model

  • Built for flexibility, creativity, not a credit box
  • One simple application process
  • Fast credit decisions and funding for transactions under $350,000
  • Personalized service with one dedicated point of contact
  • No annual financial reporting
  • Soft-cost financing (installation, freight, training, software, taxes, and warranties)
  • Industry knowledge in food processing, packaging, manufacturing, recycling, healthcare, and construction

We are not here to replace your bank relationship.
We are here to make equipment acquisitions easier and more affordable – Since 1992

​

Secure the Equipment You Need Before Prices Increase Again

Equipment Prices Are Expected to Rise – The Cost of Waiting

Equipment prices do not stand still while you wait for rates to drop. Every month of delay can mean

  • Higher equipment costs.
  • Lost productivity and revenue.
  • Missed tax benefits such as Section 179 deductions.
  • Continued use of older, less efficient equipment.

Rather than trying to time the market, many successful businesses focus on acquiring the equipment they need when it will have the greatest impact on their operations and profitability.

Take Advantage of Section 179 Tax Benefits

Purchasing equipment before year-end may provide more than operational benefits it could also create significant tax savings. Under Section 179 of the IRS tax code, qualifying businesses may be able to deduct all or a portion of the cost of eligible equipment purchased and placed into service during the tax year, subject to IRS guidelines and limitations.

Finance Equipment and Preserve Working Capital

One of the smartest ways to grow your business is to preserve cash while investing in the equipment you need.

Equipment financing allows you to acquire new equipment today without making a large upfront cash investment. Instead of tying up valuable working capital, you can spread the cost over time and match the payments with the revenue the equipment generates.

Understanding Your Credit Profile — Personal & Business

Understanding Your Personal Credit Matters

As a business owner, your personal credit profile plays a major role in the rates and financing programs available to you each year.

Section 179 & Capital Strategy Planning

Businesses can deduct the full purchase price of qualifying equipment placed in service during the tax year.

Account Receivables and Purchase Order Financing

These Programs help manage cash flow, timing, allowing businesses to operate and grow without straining traditional credit lines.

See your company’s D&B PAYDEX® score and five other Dun & Bradstreet scores and ratings

Business Credit Review: Do You Know Your D&B PAYDEX® Score?
Take a moment to review your business credit profile. Understanding your D&B PAYDEX score, business credit reporting can help you prepare for equipment financing and stronger credit approvals

Working Capital Made Simple: PO & AR Financing

Purchase Order (PO) Financing and Accounts Receivable (AR)

Purchase Order Financing

Purchase Order Financing helps when a company receives a large confirmed order but does not have enough cash to pay suppliers upfront. This funding allows them to fulfill the order without turning it down or draining their cash reserves.

These programs help manage cash flow timing, allowing businesses to operate and grow without straining traditional credit lines.

Accounts Receivable Financing

Accounts Receivable Financing helps when you have delivered your product or service but are waiting 30–180 or more days to get paid. Instead of waiting, you can access cash tied up in your invoices right away helping cover payroll, rent, materials, and day-to-day expenses.

Business Outlook 2026 – What Companies Are Planning Now

Automation & Smart Manufacturing Continue to Drive Equipment Demand

Across manufacturing, robotics, smart manufacturing, and automated systems are no longer future trends they are becoming standard investments. Companies are focused on improving efficiency, reducing labor strain, and increasing consistency through automation

We are seeing increased demand for equipment such as:

  • CNC machines
  • Robotic arms and integrated robotics systems
  • Automated cutting, packing, and sorting equipment
  • Food packaging automation

What This Means for Financing

While automation delivers long-term operational benefits, the upfront cost can be significantespecially for small and mid-sized businesses. Many companies want to move forward but prefer to preserve working capital.

Structured equipment financing allows businesses to:

  • Implement automation sooner rather than later
  • Match payments to cash flow
  • Upgrade technology without large upfront expenditures

At SCL Equipment Finance, we work with manufacturers and equipment vendors to structure payment solutions that support growth while keeping budgets predictable.

Planning Ahead: Making Financing Part of the Decision

As businesses look ahead to 2026, many are paying closer attention to interest rates, cash-flow planning, and how financing fits into longer-term decisions. Instead of waiting until a purchase is imminent, companies are having earlier conversations reviewing options and understanding potential payment structures.

The articles below offer helpful perspective on current rate conditions and how businesses are planning ahead. At SCL Equipment Finance, we support this thoughtful approach by helping clients understand financing options early, so decisions can be made with clarity and confidence when the time is right.

Read more Small Business Survey

Planning for Healthy Cash Flow

Improving cash flow often comes down to planning understanding monthly expenses, timing larger purchases carefully, and choosing payment options that keep cash available for day-to-day operations.

A Few Examples

  • Spreading out large expenses instead of paying all at once
  • Matching payments to seasonal or project-based revenue
  • Keeping cash reserves available for payroll and operating needs

6 Strategies for Accelerating Cash Flow in Your Business

At SCL Equipment Finance, we believe strong partnerships drive success. By working together, we can help your customers secure the equipment they want without financial roadblocks. Our flexible financing programs are designed to support your sales goals, strengthen customer relationships, and deliver a seamless buying experience.

Barbara Griffith, President & Founder
Monitors Top 50 Women in Equipment Financing
714-573-9804 x 101
bgriffith@sclfinance.com